
August 31, 2026
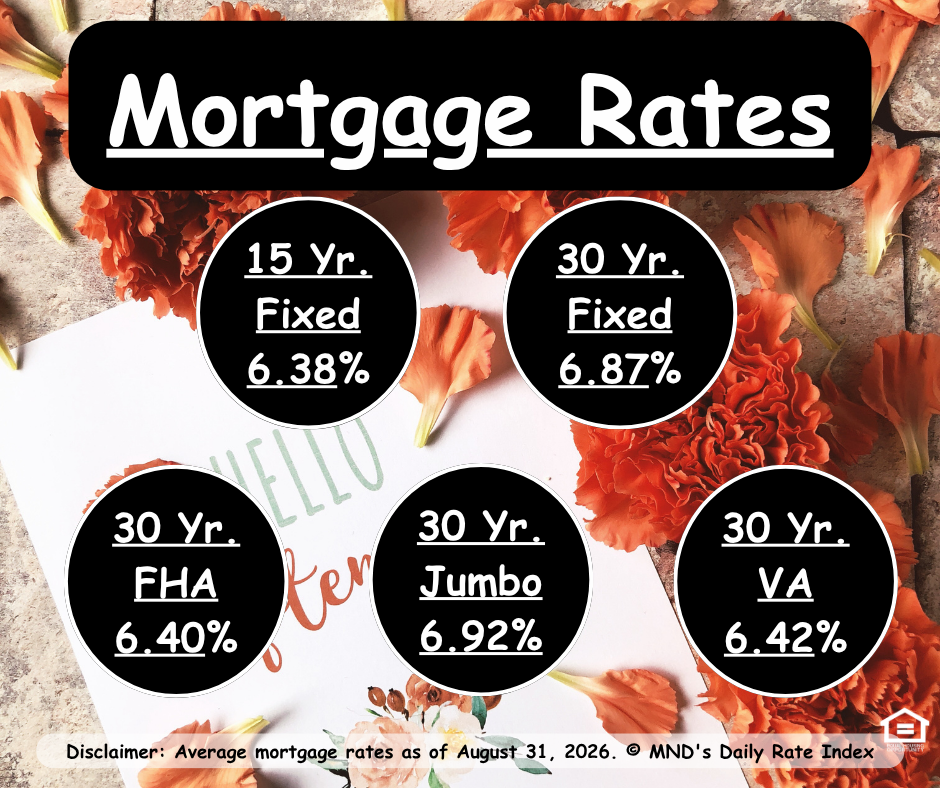
Mortgage rates are heading into September with a little turbulence.
According to Mortgage News Daily, the average top-tier 30-year fixed mortgage rate ended August around 6.87%, after moving higher during the final days of the month.
So what happened — and what does the Federal Reserve have to do with it?
🏦 The Fed Sent a Message: Inflation Still Matters
The Fed’s latest comments out of Jackson Hole caught the bond market’s attention.
The takeaway?
The Fed isn’t ready to declare victory over inflation.
Inflation remains above the Fed’s 2% target, and policymakers want stronger evidence that it is moving sustainably lower before becoming significantly more comfortable with easier monetary policy.
Markets responded quickly. Treasury yields moved higher, and mortgage rates followed.
That’s an important reminder that mortgage rates don’t wait for the Fed to officially change rates.
📉 The Fed Does NOT Set Mortgage Rates
This is one of the biggest misconceptions I hear.
When you hear “The Fed cut rates!” that does NOT automatically mean mortgage rates dropped.
The Federal Reserve controls the short-term Federal Funds Rate. Mortgage rates are influenced much more heavily by the bond market, including longer-term Treasury yields, inflation expectations and expectations for the economy.
In fact, mortgage rates frequently move before a Fed meeting because investors are trying to predict what the Fed will do next.
👀 What Could Move Mortgage Rates Lower?
There are three big things I’m watching as we move into September:
Inflation: Cooler inflation would give the Fed more confidence that price pressures are easing.
Employment: A weakening labor market could increase pressure on the Fed to loosen monetary policy.
Economic growth: Slower economic activity can generally be supportive of bonds and mortgage rates.
If the data shows inflation cooling and the economy slowing, mortgage rates could get some relief.
If inflation remains stubborn, rates could remain elevated and volatile.
🏡 Should Buyers Wait for Rates to Fall?
Trying to perfectly time mortgage rates is a little like trying to perfectly time Arizona weather. Eventually it’ll cool down — predicting the exact day is another story.
Instead of asking:
“When will rates finally hit 5%?”
I encourage buyers to ask:
“Can I comfortably afford the home today, and do I have a strategy if rates improve later?”
Waiting has a cost, too.
If rates fall, lower borrowing costs could bring more buyers back into the market — potentially increasing competition and putting upward pressure on home prices.
Meanwhile, today’s market may give buyers opportunities to negotiate:
• Seller concessions
• Temporary rate buydowns
• Permanent rate buydowns
• Purchase price reductions
• Closing-cost assistance
And if rates improve significantly later? We can look at refinancing.
🐼 The Bottom Line
Could rates improve? Absolutely.
Could we see some bumps along the way? Also absolutely.
The goal isn’t necessarily finding the perfect rate.
It’s creating the right financing strategy for the opportunity in front of you.
Thinking about buying or wondering what today’s rates would mean for your monthly payment?
Reach out and let’s run the numbers.

