
September 21, 2026
📈 The Fed Moved. Now What?
Last week gave the mortgage market plenty to chew on — and if you were expecting the Fed meeting to magically send mortgage rates lower, the market had other plans. 😏
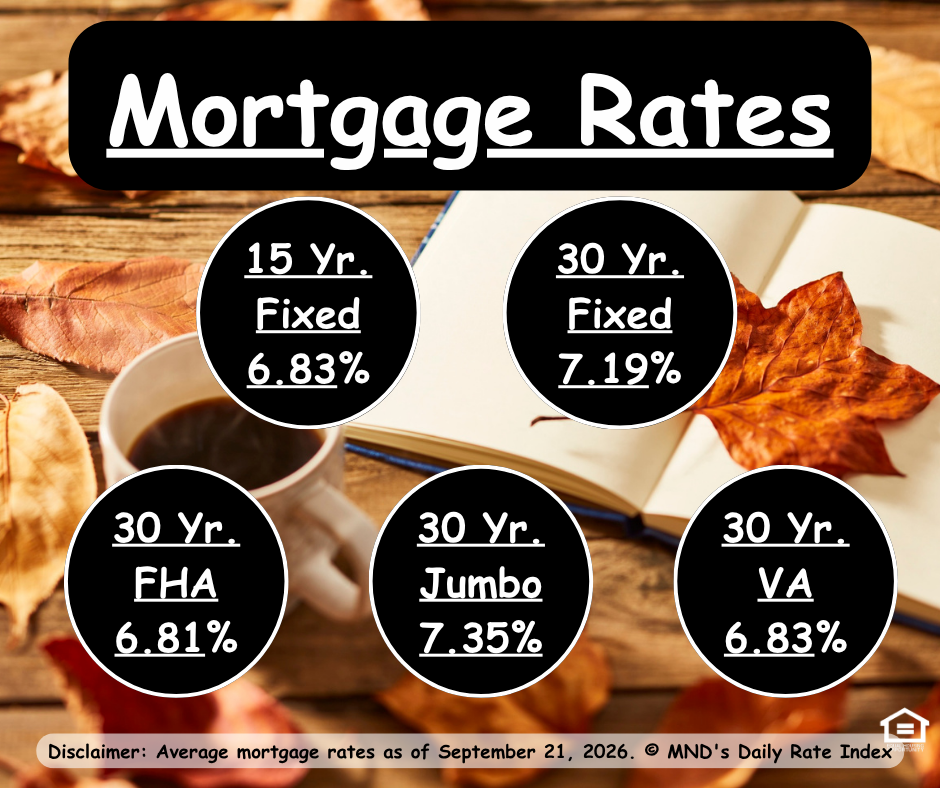
Mortgage rates climbed heading into the Fed meeting, with Mortgage News Daily’s average top-tier 30-year fixed reaching 7.24% on September 16. Rates have since settled back slightly, ending Monday around 7.19%.
🏦 Wait...didn't the Fed raise rates?
Yep. The Fed raised its benchmark rate by 0.25% last week.
But here’s the important part: the Fed does not directly set mortgage rates.
Mortgage rates are much more closely tied to the bond market and mortgage-backed securities. According to Mortgage News Daily, the Fed’s actual rate hike wasn’t what pushed mortgage rates higher. The market was reacting to the Fed’s outlook and expectations for what may happen next.
Translation: mortgage rates can move before, during and after a Fed meeting based on what the market thinks is coming — not simply because Kevin Warsh moves a lever.
🛢️ What’s moving rates now?
Inflation is still the big dog in the room, and lately oil prices have been getting plenty of attention.
Lower oil prices helped bonds improve slightly Monday, allowing mortgage rates to ease by about 0.01%. For now, however, rates remain very close to where they were before the Fed announcement.
That tells us something important: we're still in a very headline-sensitive market.
Inflation, oil prices, economic reports and Fed expectations can all create movement — sometimes quickly.
🏠 What does this mean if you're buying?
Don't let one rate headline make the decision for you.
Your interest rate is only one piece of the strategy. Purchase price, seller concessions, temporary buydowns, loan program and how long you expect to own the home can completely change the math.
There may also be opportunities in today's market to negotiate with sellers that weren't available when rates were lower and buyer competition was stronger.
Date the rate. Negotiate the house. Build the strategy around both. 🐼
🏡 And if you're selling?
Higher rates don't mean buyers disappeared. They mean affordability matters more.
Pricing correctly and being strategic with seller concessions can make a huge difference. Sometimes helping a buyer with closing costs or a temporary rate buydown can be more valuable than simply reducing the sales price.
That's why I like looking at the entire transaction instead of immediately reaching for the price-cut button.
👀 What I'm watching
The market is looking for clues about inflation and the economy — and whether the Fed's next moves will ultimately put more pressure on bonds or give mortgage rates room to improve.
For now, we're sitting near the higher end of the recent range, but that doesn't mean buyers and sellers need to sit on the sidelines.
The market isn't something we wait on. It's something we build a strategy around.
Buying, selling, or helping a client navigate this market? Let’s talk strategy. Whether you’re trying to figure out what you can afford, how to structure the right offer, or how to get a hesitant buyer off the fence, reach out. Let’s run the numbers and make the market work for you. 🐼
Market data referenced from Mortgage News Daily as of September 21, 2026. Rates shown are national averages for top-tier scenarios and are not a quote or offer to lend. Actual rates vary based on loan program, credit, property, loan amount and other factors.

