
September 14, 2026
📈 Rates Are Feeling the Pressure
📆 Fed week is here — and the market is listening closely.
If mortgage rates felt a little heavier last week, you weren't imagining it.
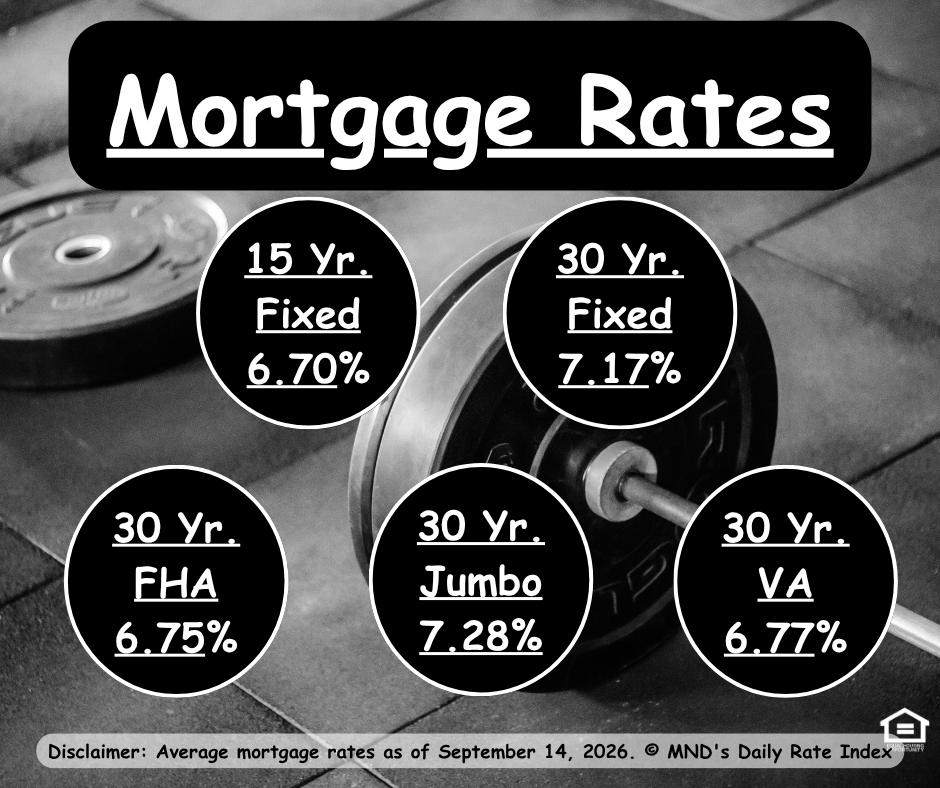
According to Mortgage News Daily, the average top-tier 30-year fixed started last week around 6.89% on September 8th and climbed to 7.17% by September 14th — the highest level since early 2025.
🔥 What Pushed Rates Higher?
It wasn't one single headline.
Rates started the week relatively calm, but the bond market quickly ran into several headwinds. A Treasury buyback announcement disappointed investors on Wednesday, followed by another jump in fuel prices and a hotter-than-hoped Producer Price Index on Thursday. By Friday, inflation data had also increased expectations that the Fed could remain more aggressive with monetary policy.
Translation: inflation is still making the bond market nervous.
And when bonds get nervous, mortgage rates usually aren't far behind.
🏦 Now All Eyes Are on the Fed
The Federal Reserve meets September 15–16, with its decision and updated economic projections coming Wednesday.
This meeting has more weight than usual because the Fed is balancing stubborn inflation against the broader economy. Even Fed Governor Christopher Waller recently said that continued improvement in inflation could support holding rates steady, while disappointing inflation data could justify another increase.
But here's the part I want buyers and agents to understand:
The Fed does not directly set mortgage rates.
Mortgage rates are driven primarily by the bond market, which is already trying to anticipate what the Fed will do. That means Wednesday's biggest market mover may not be whether the Fed changes its overnight rate — it could be the Fed's updated projections and what policymakers say about inflation and the path ahead.
🏡 What Does This Mean for Buyers?
Don't let one week's rate movement automatically put a home search on ice.
Higher rates affect buying power, absolutely. But today's market may also create opportunities to negotiate seller credits, temporary buydowns, price reductions or other financing strategies that weren't as easy to get when buyers were fighting over every house.
The question shouldn't just be, "What's today's rate?"
It should be, "What strategy makes this house work?"
That's a much better conversation.
🏷️ What Does This Mean for Sellers & Agents?
Affordability matters even more when rates move higher.
A seller credit that helps reduce a buyer's payment can sometimes be more valuable than another price reduction — and that gives us another tool when we're trying to get a deal across the finish line.
This is where the financing conversation needs to happen before the offer is written, not after.
🐼 Mama Bear Take
This probably isn't the week to make big assumptions about where rates are headed based on one headline.
Fed weeks can be volatile, and markets can move quickly in either direction as new information comes out.
I'm watching the bond market, lender pricing and Wednesday's Fed announcement closely. If you've got buyers sitting on the fence, sellers needing a better strategy, or a deal that needs some creative number-crunching, reach out.
Let's look at the whole picture and figure out what actually moves the needle.

